


How Interest Rate Changes Propagate Through the Entire Supply Chain
An ECB working paper argues that monetary policy does not affect firms only through their own borrowing conditions. Financing pressure at suppliers and customers can spread through the production network, amplifying the effects on output and prices.
The key finding: a company’s own balance sheet is only part of the story
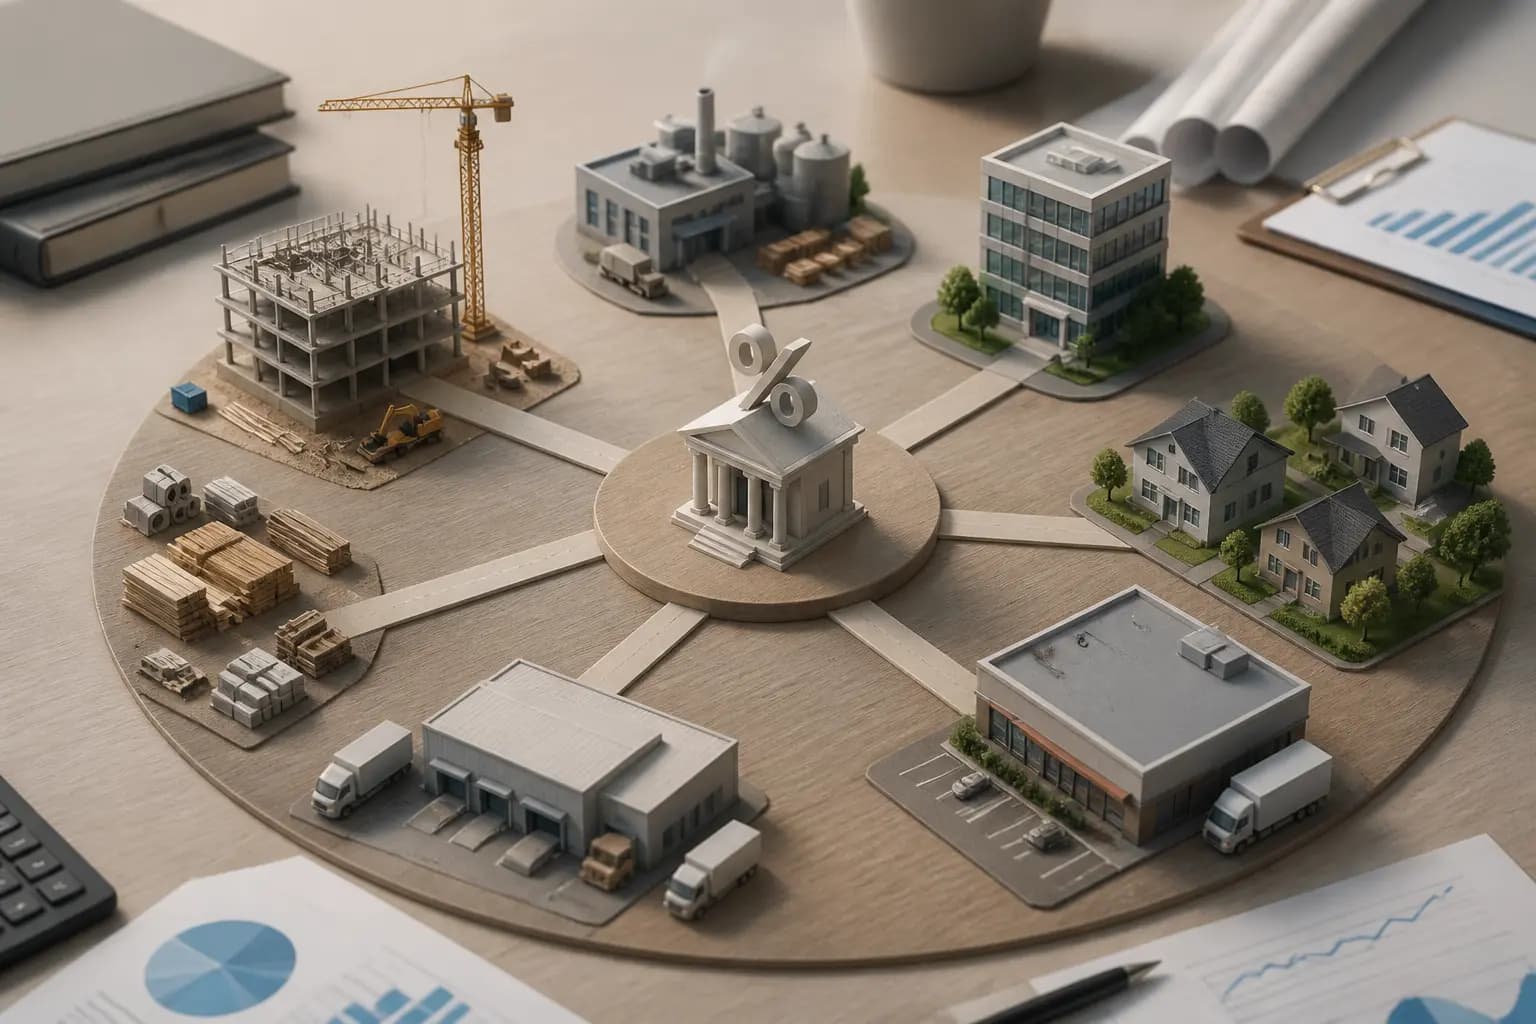
When interest rates rise or credit conditions tighten, the first question is often how much a particular company borrows. The ECB working paper points to a wider mechanism: a firm can also be affected by the financial constraints of the businesses connected to it.
Those connections run through the production network. A manufacturer depends on suppliers for inputs, while its own customers depend on it for components or finished goods. If financing becomes more difficult anywhere in that chain, the consequences can reach firms that were not initially the main target of the tightening.
The paper studies this process in a multi-sector general-equilibrium model that includes input-output relationships and working-capital constraints. Its central result is that indirect financial frictions in the broader network amplify the effects of monetary policy and, empirically, are more important than direct frictions within a sector itself. *(Source: S1.)*
Two channels push the economy in opposite directions
The paper identifies a downstream demand channel. When policy becomes tighter, customers respond by buying fewer inputs. That reduces demand for suppliers and can weaken activity further down the network. In practical terms, a financing shock can become a sales shock for firms whose own borrowing position has not changed as much. *(Source: S1.)*
There is also an upstream cost channel. Suppliers facing higher financing costs may raise prices to protect their margins. This can pass higher costs to downstream businesses, partly offsetting the demand reduction. The result is not a simple one-way story in which tighter policy always lowers every price immediately: weaker demand and higher supplier prices can operate at the same time. *(Source: S1.)*
The important distinction is between the direct effect—a firm’s own financing conditions—and the indirect effect created by its commercial relationships. According to the paper, the latter dominates empirically in the mechanism it examines. *(Source: S1.)*
Why this matters for mortgage planning
For a household considering a property purchase, this research does not provide a mortgage-rate forecast or a rule for when to buy. Its value is different: it offers a more realistic way to think about how monetary policy reaches household finances.
Interest rates can affect more than the monthly cost of a new loan. Through businesses and their suppliers, tighter financing may influence production, input prices, hiring plans and income stability. These effects are not uniform, and the source does not quantify their impact on a particular household or property market. They should therefore be treated as a transmission framework, not as a personal financial prediction.
A robust mortgage decision should test the household budget against several pressures at once:
- the loan payment under the offered rate and a higher-rate scenario;
- essential living costs if supplier prices remain elevated;
- income resilience if the borrower’s sector or customers face weaker demand;
- cash reserves for repairs, vacancies or other property-related costs;
- the difference between a comfortable payment and the maximum amount a lender might consider.
This approach reflects the production-network insight without pretending that every borrower will experience the same outcome.
The practical lesson: watch cash flow, not only the headline rate
A single policy rate is easy to track, but it is only one input into the household decision. The transmission described in the paper suggests that the timing and size of effects can depend on how financial pressure moves through connected sectors.
For property planning, that makes cash-flow resilience especially important. A buyer who focuses only on the initial mortgage payment may overlook changes in household expenses or employment conditions. Conversely, a temporary increase in input costs does not automatically mean that a specific household will face a lasting income shock.
The useful question is therefore not simply, “Where will rates go?” It is: “Would this budget remain workable if financing pressure affected both my borrowing costs and the wider economy?” That question can be tested with conservative assumptions, without relying on a precise forecast.
What the research does—and does not—establish
The ECB working paper provides a model-based explanation for why financial frictions across production networks can magnify monetary policy’s effects on output and prices. It does not, in the supplied source material, establish a specific forecast for mortgage rates, house prices, wages or an individual borrower’s employment prospects. *(Source: S1.)*
That boundary matters. The research improves the map of how shocks can travel; it does not remove uncertainty about the destination. For a long-term financial commitment, the sensible response is to combine the macroeconomic framework with the borrower’s own income security, reserves, debt structure and property costs.
*Calculations and examples are illustrative and do not replace financial, investment or mortgage advice.*
Key takeaways and FAQs
What are financial frictions in a production network?
They are financing constraints that affect firms and their commercial partners. The research argues that these constraints can spread through supplier and customer relationships, rather than remaining confined to one sector.
How can tighter monetary policy affect suppliers?
The source describes two channels: customers may purchase fewer inputs, weakening demand, while suppliers may raise prices to protect margins when financing costs rise.
Does this research predict mortgage rates or house prices?
No. The supplied source explains a mechanism for monetary policy transmission, but it does not provide a specific mortgage-rate or property-price forecast.
What to take away
The main insight is easy to miss when monetary policy is viewed only through a borrower’s own interest rate. Financial pressure can travel through suppliers and customers, reducing demand in some parts of the network while raising costs in others. For property decisions, the practical response is not to make a precise macroeconomic bet. It is to test whether the household budget can withstand higher borrowing costs, changing expenses and weaker income conditions at the same time.
This article is informational and does not replace financial, investment or mortgage advice.


